Europe has an opportunity to deepen its capital markets through the EU’s Market Integration and Supervision Package (MISP), but reforms should reduce fragmentation and complexity without reopening regulatory debates that could undermine competitiveness, speakers at FIA Forum Madrid said.
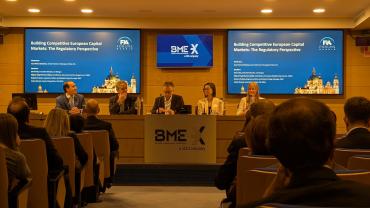
Emma Tan, executive director at JP Morgan, described the EU as being at a “critical juncture”, with the longstanding ambition of creating a single European market yet to be fully realised. Fragmentation remains a key obstacle, she said, pointing to different regulatory expectations and interpretations of existing rules that firms encounter across Europe.
Greater harmonisation could make cross-border business easier, but Tan cautioned against revisiting old debates, including open access for exchange-traded derivatives.
“We need to focus on the things that will really move the needle for European markets,” she said. Tan added that regulation alone could not create deeper capital markets, pointing to the need to encourage greater investor participation and shift Europe from a savings mindset towards an investment mentality.
Miguel Ángel Herrero Alvite, coordinator, Secondary Markets Department at Spain’s market regulator CNMV, said progress towards a less fragmented market was likely to be gradual. Success, he said, would include more companies accessing capital markets, greater investor participation, lower administrative and compliance burdens, and improved international competitiveness for EU markets, infrastructure and companies.
On supervision, Herrero Alvite stressed the importance of proportionality. While enhanced or more harmonised supervision may be appropriate for significant market infrastructures, he argued that smaller entities should not necessarily be treated in the same way. Having a supervisory authority close to the market infrastructure it oversees could make supervision more proportionate and efficient, he said.
Simplification
For corporate end users, simplification and burden reduction should be at the heart of MISP, said Roberta Premm, regulatory affairs and market design manager at energy company RWE.
Premm backed the longer-term goal of a “report once” framework, alongside shorter-term “quick wins” including mandatory delegated reporting and streamlining the intra-group reporting exemption process. Such changes could benefit non-financial counterparties without requiring significant upfront implementation work, she said.
She also questioned proposals to revisit areas including the ancillary activities exemption and position limits regime, arguing that doing so risked creating additional burdens at a time when the EU is seeking to improve competitiveness.
“Why do we now open something that clearly works and not stick to the clearly defined agenda of the EU, which is making the EU more competitive and delivering on the simplification and burden reduction agenda?” Premm said.
Carles Torrent, head of regulation CIB at Spanish bank BBVA, likewise identified efficiency and simplification as priorities. While supporting efforts to streamline transaction reporting, he cautioned against rushing reforms through MISP only to require further adjustments later.
Torrent also pointed to the sequencing of EU rules as an area for improvement, including a lack of synchronisation between Level 1 legislation and the detailed Level 2 measures needed for implementation. Greater powers for ESMA to provide regulatory certainty, including through no-action letters, would also be important, he said.
Herrero Alvite said he shared the industry’s concerns about Level 1 and Level 2 sequencing, noting that implementation challenges affect supervisors as well as firms, because authorities are responsible for overseeing compliance with requirements that firms may not yet be ready to meet. He said he would favour ESMA having greater scope to provide firms with legal certainty in such circumstances.
The issue is also addressed in FIA’s recent paper, A Pathway to Smarter Regulation in Financial Services, which calls for better sequencing so that detailed implementing rules are available before firms are expected to comply with new obligations. The paper also explores longer-term reforms that could give ESMA the power to issue legally binding no-action relief in defined circumstances.
Active accounts
The panel also discussed EMIR 3.0’s active account requirement, which requires certain EU financial and non-financial counterparties to maintain an active, operational account at an EU CCP. ESMA is due to assess the effectiveness of the requirement, including whether it has addressed EU concerns about dependencies on third-country Tier 2 CCPs.
Tan said that, viewed purely in terms of account openings, the requirement has been successful. EU clients have opened accounts at EU CCPs, meaning that if the objective was to establish a back-up clearing account in the event of financial stability problems at a UK CCP, that objective had been achieved.
However, she distinguished that objective from the broader question of how much clearing activity should move into the EU.
Implementation has been complex, she said, including compliance with the active account representativeness requirements, while European clients can be at a relative disadvantage to non-EU clients that do not face the same restrictions.
Tan said the fact that significant volumes have remained at UK CCPs should not be seen as a sign that the active account requirement has failed. Rather, she said, it reflects the tendency for activity to gravitate towards liquidity and the greatest margin benefits.
Tan argued that policymakers should focus more on incentives to clear in Europe rather than additional mandatory requirements.
BBVA’s Torrent said the requirement had also been difficult for BBVA to implement because the bank both trades for its own needs and services clients that choose where their transactions are cleared. Compliance becomes particularly challenging for less-liquid instruments that trade less frequently, he said.
If the framework is too restrictive, the outcome may not be to move the trade to an EU CCP, but instead to leave an EU bank unable to service the client, potentially resulting in a loss of competitiveness, Torrent said.
He added that any objective for the amount of business cleared at EU CCPs should reflect the proportion of EU clients and counterparties participating in the market.
CNMV’s Herrero Alvite said the effects differ depending on the type of market participant. Smaller firms may be less sensitive to differences in clearing costs, while larger institutions with complex portfolios can face materially different costs, particularly where exposures across products or currencies can offset one another. If EU firms face different costs from competitors elsewhere, “they could have an added disadvantage”.
He said ESMA’s review would also need to consider whether the financial stability risks that prompted the active account requirement had been reduced, and whether the benefits of any additional measures would outweigh their costs.
Jean Pierre Salendres, senior director of European policy at FIA and moderator of the panel, said FIA had favoured measures aimed at improving the competitiveness of EU CCPs. FIA would not recommend additional measures around the active account requirement, he said.
Innovation
The panel also looked beyond the immediate regulatory agenda to tokenisation, prediction markets and artificial intelligence.
Tan said markets were at a potential turning point in areas including tokenisation and tokenised collateral, moving from the pilot stage towards wider deployment. However, scaling these would require firms and regulators to address issues including legal certainty and settlement finality.
Prediction markets raise a different set of questions, she said, including market integrity, how insider information should be defined for non-traditional contracts and where the regulatory boundary lies between a derivative and gambling. Robust legal, regulatory and risk-management frameworks would be needed for such markets to develop sustainably, Tan said.
Torrent said other jurisdictions are adapting their regulation and infrastructure to enable tokenisation and argued that the EU “cannot be behind on this”. He also highlighted tokenised collateral as a potential way to make collateral management more efficient.
Herrero Alvite said tokenisation was an area of particular interest because of its potential to improve market efficiency. He also highlighted artificial intelligence, cyber security and operational resilience as areas regulators need to understand as financial services become increasingly dependent on technology.
More broadly, Herrero Alvite said the immediate priority should be to consolidate and simplify the EU’s existing regulatory framework. After almost two decades of rulemaking since the financial crisis, he said regulation covering most market activities had reached a relatively mature stage.
“For me, it’s not [about] trying to issue more regulation, but consolidating the ones that we already have,” he said.
