Perpetual futures are moving beyond their crypto roots and into regulated US derivatives markets, raising questions about how they should be classified and which rules should apply.
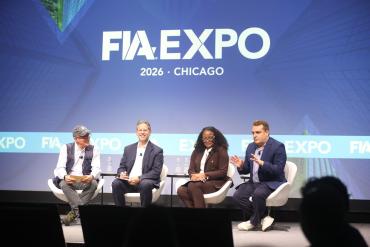
The issue was at the centre of a panel discussion at FIA Expo in Chicago on 3 November featuring Jeff Bandman, chief executive officer of Kalshi Prime; Boris Ilyevsky, head of US markets at Coinbase; and Tamika Bent, a partner at K&L Gates. The discussion was moderated by Gary DeWaal, a former senior counsel at Katten Muchin Rosenman.
Unlike conventional futures, perpetuals have no fixed expiry. Instead, periodic funding payments between long and short positions keep the contract price close to the price of the underlying asset, removing the need for traders to roll positions from one contract month to another.
Ilyevsky described perpetuals as a retail-friendly product, while saying the structure could also be attractive to institutional participants. Coinbase currently offers perpetual futures based on cryptocurrencies and US equity indices to customers in the US. In addition, it offers conventional dated futures on commodities to customers in the US, and commodity perpetuals to non-US customers through its international trading venues.
Bandman similarly argued that perpetuals could appeal to institutions for both hedging and speculation. He said commodities such as gold and WTI crude now account for around 25% to 30% of Kalshi's perpetuals business, while the model is also being extended to equity indices and individual stocks.
The growing popularity of perpetual contracts has also raised a more fundamental regulatory question: are they futures at all?
Future or swap?
Bent, a former chief counsel to CFTC Commissioner Kristin Johnson, said the Commodity Exchange Act, the main US law governing derivatives markets, does not provide a straightforward definition of a futures contract. Instead, it refers to contracts for the sale of a commodity for "future delivery".
That creates an unusual legal question for a contract with no scheduled expiry. The Commodity Futures Trading Commission addressed the issue on 29 May when it approved Kalshi's BTCPERP contract, which references the spot price of bitcoin, for listing as a futures contract.
Bent said the CFTC focused on convergence in its rationale for approval. A conventional future ultimately converges with the price of its underlying market through delivery or cash settlement. A perpetual has no fixed expiry, but the commission concluded that periodic funding payments can perform a similar function by keeping the two prices aligned.
DeWaal raised the other side of the argument: if those funding payments flow one way or the other depending on whether the perpetual trades above or below the underlying, why should they not be regarded as an exchange of cash flows, potentially pointing towards a swap?
Ilyevsky, who said he was not a lawyer, answered that the mechanism exists to keep the perpetual in line with the spot asset. "It is not an exchange of cash flows," he said.
The panel did not settle the legal question, but Bent made clear that the classification has practical consequences for market participants.
"There is an entirely different regulatory framework for futures versus swaps," she said, adding that the classification can affect who can trade the products, how they are cleared and how customer assets are treated for segregation.
Single-stock perps
The issue became more immediate on the day of the Expo discussion. Earlier that morning, the CFTC announced that properly registered commodity markets could begin trading single-stock perpetuals as security futures.
The Capital Markets Alliance, a newly formed group that includes Cboe Global Markets and Citadel Securities, then filed suit in a US District Court challenging the CFTC's approval, arguing that the contracts are security-based swaps, rather than security futures, and that the approvals violate the Administrative Procedure Act.
Bent explained the significance of that distinction. Security futures fall under the joint authority of the CFTC and the Securities and Exchange Commission. Exchanges, futures commission merchants and clearinghouses that list security futures can notice-register with the SEC and keep complying with CFTC rules.
On the other hand, if the contracts are security-based swaps, "the primary issue here is that they are only subject to the SEC's regime," she said. Security-based swaps must trade on a national securities exchange.
Bandman argued that the boundary between futures and swaps has shifted before as financial products have developed. He also suggested that opposition to perpetuals reflected competitive concerns among established exchanges.
In particular, he argued that perpetuals present a competitive challenge to conventional futures because traders do not have to keep rolling their positions as contracts expire. For exchanges, he said, that removes the recurring trading associated with moving positions from one contract to the next.
"This wouldn't be the first time in history that an incumbent was threatened by a new product and used legal means to try to challenge it," he said. “It won't be the last time either."
Cboe has rejected the suggestion that the dispute is simply commercial. In a statement issued in conjunction with the lawsuit against the CFTC, the exchange's chief executive Craig Donohue said the company's concerns centre on investor protection and the regulatory framework governing US securities markets.
"Cboe has joined this action alongside some of the largest US market participants and investor advocates because we believe the CFTC's actions threaten to erode the regulatory framework that has protected investors and governed US securities markets for more than nine decades," Donohue said in the statement.
"Single-stock perpetual derivatives are the latest example of a troubling trend in which securities products are being offered on CFTC platforms – outside the appropriate regulatory framework and customer protection regime established by Congress," he added. "Whether tied to individual issuers, broad-based security indices, corporate events, or other securities-related outcomes, these securities products belong on registered securities platforms and should be subject to the investor protections, oversight and safeguards required under US securities laws."
Since the Expo discussion, several firms offering or active in perpetual markets have backed the CFTC. Coinbase, Kalshi, Payward, DRW, Jump Trading and Paradigm filed a proposed amicus brief on 9 November opposing the Capital Markets Alliance's request for a preliminary injunction. They argue that single-stock perpetuals qualify as security futures and warned that blocking the contracts would push the market back offshore.
On the panel, Bandman stressed the protections that come with futures status. When the product came onshore, he said, it was not simply copied from the offshore version. Instead, it was brought under a central counterparty with protection for customer collateral. Those who trade it do so "in a regulated market with all the CFTC customer protections that we all know and love with the whole ecosystem", where customer protection is tied into the bankruptcy code.
Manipulation concerns
Legal classification is not the only question surrounding perpetuals. DeWaal asked whether the products' frequent funding resets make perpetuals easier to manipulate.
Bandman rejected comparisons between regulated US perpetuals and products offered by offshore venues without comparable controls. He pointed to trade and market surveillance and central clearing as safeguards in regulated US futures markets.
"People have these conceptions about what happens in the illegal offshore markets and then they impute it to the onshore regulated markets," he said.
For all the regulatory and legal debate over classification, Ilyevsky argued that end users take a more practical view. They care whether the product meets their needs, whether the exchange and order book are liquid, and how the leverage looks and feels, he said.
"I think for all intents and purposes, ultimate clients, be they retail or institutional, don't care," he said.
