Clearinghouses and their members have absorbed sharp bouts of market volatility and rising margin requirements without major disruption, but attention is shifting to whether clearing members and clients can anticipate margin needs and mobilise collateral quickly enough when markets move.
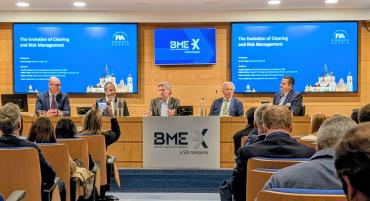
Executives from UBS, Santander and SIX outlined those pressures at FIA Forum Madrid on 29 October, as they considered how clearing is adapting to volatile markets, greater demands for margin transparency and potentially longer trading hours.
During the tariff-driven market turbulence in April 2025, SIX-owned BME Clearing issued relevant sizeable intraday margin calls, according to Ataulfo Argenta, head of clearing business development at SIX Clearing. All its clearing members met the calls.
The episode showed that clearing members could absorb significant liquidity demands under stress, Argenta said, but resilience also depends on operational capacity and coordination across the clearing chain. The challenge is maintaining that discipline as markets move faster, operational windows shorten and clients demand information closer to real time, he added.
Robert Mawby, EMEA Head of Clearing at UBS, said technology investment had enabled the industry to process greater volumes and aggregate data in real time, allowing decisions around intraday margin calls to be made and communicated quickly, although managing periods of market stress still requires human judgement.
Technology can identify when action may be needed, Mawby said, but deciding how to respond still requires an understanding of the individual client, backed by experience, established relationships and communication.
Liquidity management
Large institutional clients are also asking clearing banks for more information about their potential margin and funding needs.
Gilbert Sintes, head of ETD Europe and global head of sales at Santander, said clients increasingly expect clearing to be connected with their broader management of risk, liquidity, funding and collateral.
“They view clearing no longer as just a standalone post-trade service,” he said. Conversations increasingly cover what collateral clients should post, how much it will cost and the potential effect on their funding.
The shift is also making clearing more strategic within financial institutions, Sintes said, with clearing now extending beyond operations to collateral management, treasury, asset and liability and trading.
Closer coordination across those functions has become more important as sharp market moves translate into higher initial margin requirements, putting pressure on clearing members and clients to manage liquidity and mobilise collateral.
Clients also want that information faster. Mawby said banks’ investments in intraday and real-time data means it has the data available within its infrastructure.
“The question then becomes how do we deliver that data to the client? Which of our integration options is the right fit for this situation?” he said. This is where how clients use that information matters, whether to make risk decisions or resolve breaks and reconciliations.
“It’s those conversations that really add value beyond ‘I’m offering you clearing, I’m doing it by this technology’,” he said. “Going beyond that and helping them enhance their operations, I think is the key.”
Technology providers are developing tools to give clearing members that visibility. Peter Fredriksson, managing director at SIX-owned Baymarkets, said its Clara clearing platform provides operational and risk dashboards covering areas including margin calls and settlement problems. Users can also simulate how a portfolio or individual contract would affect margin requirements.
SIX acquired Baymarkets in November 2025 as part of its strategy to strengthen its clearing technology.
Different models
European rules are also pushing CCPs and clearing firms to give market participants a clearer view of potential margin requirements.
Under EMIR 3.0, CCPs must provide clearing members with tools to simulate the additional initial margin that could result from new transactions at portfolio level and under different scenarios. They must also provide information explaining how their initial margin models operate, including their key assumptions and limitations.
ESMA's technical standards address CCP margin model information and simulation tools, as well as margin model information and simulations provided by clearing service providers to clients.
Giving clients a meaningful picture of future margin requirements is complicated, however, by the different models used by CCPs.
A client may clear at 10 or 20 CCPs through the same clearing member, Mawby explained. Applying the same historical scenario across those positions requires the clearing firm to understand how each CCP's model would respond for that specific scenario or for that specific portfolio.
The amount of information available about those models also varies. CCPs may compete on their margin methodologies, making them part of their innovation and intellectual capital, Mawby said.
Questions also remain over how some of the new requirements should work in practice, including who should define the scenarios used for margin simulations. CCPs may see that as the responsibility of clearing members, while clearing members may look to CCPs, Mawby said.
“That’s where the FIA and industry bodies can make a big difference in trying to guide that alignment,” he said.
Argenta cautioned against treating greater transparency as a reason to standardise CCP margin models or expect identical outcomes. CCPs already publish significant amounts of information under existing disclosure requirements, he said. “I see it more like an evolution, not a revolution,” he added.
Clearing banks sit between CCPs and their clients, meaning their ability to provide useful margin forecasts depends partly on the information and simulation capabilities available from the CCPs themselves.
“We desperately need the CCPs to provide us with the simulation tools so we can start,” Sintes said.
Technology
As markets move closer to real time, AI and tokenisation offer potential efficiencies, but neither provides an immediate answer to the industry's liquidity challenges, panellists said.
Fredriksson said AI could improve efficiency in areas such as margin prediction and collateral management. He was more cautious about applying it to critical CCP decisions, including default management and suspending members, where human intervention would be required.
Tokenisation faces a different hurdle, he added. Tokenised assets already operate across different networks, but those networks need greater interoperability before the technology can be widely incorporated into existing trading and clearing systems.
For Mawby, the opportunity is to focus new technology on the areas where it can deliver the greatest value for clients. “It feels like historically we identified a problem and then sought to understand how we use technology to solve it. Now we have the technology, the key is selecting the right problems to apply it to,” he said.
The industry has run numerous pilots and use cases, but clients increasingly want solutions with tangible benefits, he said. Adding another way to transfer collateral could increase complexity if existing processes still have to be maintained alongside it.
24/7 availability
The case for tokenised collateral could become stronger if trading moves towards 24/7 availability. Being able to transfer assets outside conventional operating hours could help support an always-on market, but that requires the wider chain of clients, banks, custodians, payment providers and CCPs to support it, Mawby said.
Argenta also cautioned against assuming that longer trading hours would automatically create more liquidity. Extending hours could instead spread existing liquidity across a longer period, potentially leaving thinner order books and wider spreads at certain times. The case for 24/7 trading should therefore be assessed by product and according to client demand, he said.
Continuous trading would also require clearing and risk management to adapt, including margin calls, collateral mobility, staffing, default management and liquidity provision.
Ultimately, the challenge is not simply calculating margin requirements around the clock, but ensuring clearing members can mobilise the collateral needed to meet them.
Argenta said he was not sceptical about the direction of travel of new technologies but favoured a cautious approach based on specific products, real-world use cases and the ability of the wider infrastructure to support them safely.
