The rise of retail trading since the Covid pandemic has been one of the biggest drivers of change in the US options market in recent years, but it’s not the only one. There have also been big changes on the institutional side of the business, especially in how the options markets interact with exchange-traded funds.
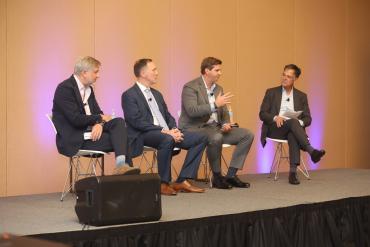
At a panel discussion on 3 November at FIA Expo in Chicago, executives from across the equity options ecosystem talked about how this interaction has created a virtuous cycle of liquidity, with growth and innovation in both sets of products reinforcing each other. As Paul Jiganti, the panel moderator and a managing director at IMC, said during the discussion, the ETF industry and the options markets are all part of one "ecosystem" that is growing at a rate that amazes even industry insiders.
Central to this virtuous cycle has been the massive growth in the assets invested in ETFs as millions of Americans have found them to be an inexpensive and efficient way to add market exposure to their investment portfolios. Total assets under management across all ETFs reached $16 trillion as of September, which is equivalent to about half the amount invested in pension funds and more than double the amount invested in US hedge funds.
The trading of options on these ETFs has also become a big business. Trading volume has averaged more than 28 million contracts per day so far this year, up 28% from last year and four times larger than 2019, the year before the Covid pandemic.
Innovation also has been a key factor. In the last five years, a new type of ETF has emerged that embeds options strategies in the fund's investment strategy. In some cases, these ETFs use a covered call strategy, selling calls to add income to the return on the underlying portfolio of stocks.
In other cases, these ETFs use options for downside protection, buying puts to buffer the value of the portfolio in case of a stock market decline. This latter group is often described as "defined outcome ETFs" and they have proven to be especially popular with older investors worried about taking a loss as they enter retirement.
According to data published by Cboe, there are currently around 1,000 of these option strategy ETFs with roughly $350 billion in assets under management. And the business is booming – both numbers are roughly double what they were a year ago.
That leads to a significant amount of trading in flex options, a sector of the options market that caters to institutional investors. These contracts can be tailored to specific maturities and strike prices, and they are the instrument of choice for portfolio managers running options strategy ETFs.
According to the Cboe data, volume for flex options has averaged 2.1 million contracts per day so far this year. Although that's a small share of the overall options industry volume, it is a huge jump from prior years. Flex option ADV was 1.4 million last year, and just 129,000 in 2019.
Investor appetite
To get a better sense of the view from inside the ETF world, FIA invited Ted Samulowitz, head of North American alternative ETFs at Invesco, to join the discussion at the Chicago conference. Invesco is the fourth largest ETF provider in the US, with $980 billion in assets under management in more than 250 funds, and it is a leader in the development of options strategy ETFs.
Samulowitz explained that demand for this new type of ETF has come from at least three factors: the aging of the investor population; the long period of low interest rates after the financial crisis of 2008; and more recently, the sharp increase in market volatility.
“I think the biggest one is the transition of the baby boomers into retirement," he said. "They have $70 trillion in assets, they are looking for yield, and they are also looking to protect their assets,” he said.
The prolonged period of low interest rates following the financial crisis also made yield harder to find through traditional investments, he said. The market disruption during the Covid pandemic then provided a test for option strategies designed to offer investors downside protection.
Another perspective on this trend came from Slade Winchester, who manages low-touch execution for equity derivatives at Goldman Sachs. Winchester noted that registered investment advisors have been drawn to option strategy ETFs because they can give their clients access to strategies they might not otherwise be able to use.
“You are buying into some very sophisticated strategies that normally people would not have access to,” Winchester said.
The growth of options-based investment strategies is also making retail financial advisors more comfortable with these derivatives. “One of the nice things with all this growth in options and the strategies is the sophistication level is slowly creeping up,” Samulowitz said.
Samulowitz also highlighted the importance of a technical change in how these funds operate.
In 2019, the Securities and Exchange Commission approved a Cboe rule allowing the in-kind transfer of options for options-based ETFs. This rule enabled options-based ETFs to execute creations and redemptions with options rather than cash-only transactions.
This change in the mechanics of fund operation allowed the funds to avoid realising taxable capital gains and allowed investors in these funds to defer taxes until they sold their shares, which helped open the door to greater use of option strategies in ETFs and spurred the growth in the trading of flex options.
“Ten years ago, if you told me all the ETF providers would be trading flex options, I would not have believed it,” Samulowitz said.
Inside the options workshop
The growth of equity options strategies has brought ETF managers, banks, market makers and other liquidity providers into closer collaboration.
Ideas for new products come from portfolio managers, quantitative strategy teams at banks, and index providers such as Nasdaq, according to Samulowitz. But the ideas that receive the most immediate attention often come from Invesco's clients. If a client proposes a strategy that could appeal to other investors and can provide assets to help seed the product, the idea is likely to move up the list, he said.
The relationship between ETF managers and liquidity providers has also evolved. Samulowitz said market-making firms that once concentrated primarily on quoting prices are now helping managers seed products, execute swaps and support the wider trading ecosystem. “Now it feels like we're all kind of working together to the same end,” he said.
Liam Smith, chief strategy officer at Optiver US, a proprietary market-making firm, agreed, saying market makers are increasingly taking a holistic approach to helping asset managers launch new products.
That can include acting as lead market maker for an ETF, providing liquidity in related options, supporting the underlying package of assets and, in some cases, helping to provide the initial seed capital.
But the number of new ETFs means liquidity providers cannot support every launch equally.
“Obviously you want to help everybody, but also there is so much that is being launched on a regular basis,” Smith said. Market makers therefore have to be selective about which new products they can realistically support.
Winchester commented that this activity is having a "flywheel effect" on the overall liquidity of the market. The market makers that take the other side of the flex options traded by the ETF providers then go into the market to hedge their risk.
"So volume begets volume and liquidity begets liquidity," he said. "People post tighter bids and offers, and then retail is interacting with that. This is like adding a bellows to the fire of the volume that we have been getting in the marketplace [and] a real tailwind to the industry."
Samulowitz added that Invesco sees these trends as reinforcing the liquidity of its ETFs, which in turn makes them more attractive to investors.
"We push hard to get options listed on our funds because it draws more flow," he explained. If people are trading the options, the market makers have to hedge their exposures, and that leads them to trade more shares in the underlying ETF. "So it is a total win-win for us to have a really vibrant options market within our strategies."
Looking ahead
Despite the dramatic growth, demand for options-based ETFs and options linked to ETFs shows little sign of slowing.
“Our expectations are this ETF distribution channel will continue to be a really strong channel for the market,” Smith said.
Another factor is the growing number of options with expirations on every day of the week, rather than limited to the end of the month. This has encouraged trading in short-dated options, and especially "zero days to expiration" options. These 0DTE options now account for more than two-thirds of all trading in SPY options, the most actively traded ETF option in the US.
The fact that these options are now so liquid makes it possible for liquidity providers to hedge their risk much more precisely, and that is allowing them to extend their liquidity provision into other sectors of the options markets.
Smith explained that the evolution of the market maker business model has moved from "going home flat", meaning that a firm would end the day with no risk exposure to a market move either up or down. Now market makers are in the business of "warehousing risk" and therefore are looking for more ways to hedge that risk. That might have been through the futures market in the past, but the growth in short-dated options has given market makers another way to hedge.
More waves of innovation
One possible challenge to the growth trend is the emergence of perpetual futures. In contrast to conventional futures, "perps" have no expiration. Their primary use case to date has been in the offshore crypto markets, where they account for the majority of trading volume, but the Commodity Futures Trading Commission has allowed onshore exchanges to list these products and many observers expect them to attract retail traders looking for leverage.
Smith agreed that the launch of perpetual futures on stock indices and individual stocks gives traders an alternative way to get exposure to the underlying market, and said it could pull some volume away from the options markets, and especially short-dated options.
“Short-dated options have become so liquid and so active, a lot of firms use that as hedging as well. If it [perps] became a better hedging tool, who knows? I could see groups looking at that as another way to manage their book,” Smith added.
On the other hand, Smith noted that there is another recent innovation that could drive even more volume in the options industry – the introduction of KPI options. These are binary options on company-specific key performance indicators, such as the number of cars sold by Tesla or the earnings per share reported by Microsoft. These contracts were introduced this year by Kalshi, the prediction market regulated by the CFTC, and several options exchanges are seeking SEC approval to launch their own suites of KPI options.
Winchester cautioned, however, that KPI options have one feature that may result in fragmenting liquidity. In contrast to ETF options, which have the same underlying no matter which exchange they are traded on, there may be variations in how each exchange defines the terms of the contract. That would lead to variations in price, which runs the risk of confusing investors.
Blurring the lines
Technology is another factor that is driving the growth of the options markets. Winchester said large multi-strategy hedge funds are increasingly using sophisticated technology to participate in auctions, a mechanism used by options exchanges to provide better price discovery. In these auctions, exchanges expose customer orders to the market for a fraction of a second so that broker-dealers, market makers and other participants can compete to offer a better execution price.
Winchester said these hedge funds are building systems capable of responding to options auctions within 100 milliseconds – an activity that was once largely associated with specialist market makers.
"There is a lot of competition for this growing order flow and new entrants thinking about how they provide liquidity in the marketplace," he said.
Smith noted another trend in technology that is encouraging more trading. New artificial intelligence tools are allowing firms to develop sophisticated technology more quickly, paving the way for a broader range of market participants to engage in options trading.
"This is no secret – lots of hedge funds are trying to move closer to market maker kind of structures," he said. While in the past they did not have the right "tooling" in their trading systems to compete with market makers, he said that has changed with the advances in AI.
“It is allowing a lot more people to participate at a very high level and to spin up things quite quickly as well,” he said.
