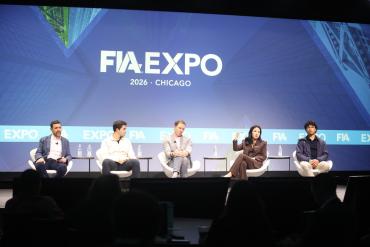
The rapid buildout of AI infrastructure has created growing demand for ways to hedge the cost of compute, but benchmark providers speaking at FIA’s Futures & Options Expo in Chicago disagreed on what those contracts should track and how quickly a liquid market could develop.
Andrawes Bahou, chief executive officer of Compute Desk, a benchmark administrator that licenses compute indices to exchanges, said lenders financing new GPU clusters typically require the operator to secure a creditworthy customer on a three-to-five-year reservation before they will provide financing. Those reservations lock in the cost of accessing the computing capacity used to train and run AI models, while giving lenders greater certainty that the investment will generate revenue.
Bahou said long-term reservations are currently the main way operators hedge their exposure in the over-the-counter market.
Wayne Nelms, co-founder and chief technology officer of compute market and index provider ORNN, said the people with the most exposure are those financing GPU infrastructure “with no benchmark.” In his view, a data centre cannot quickly swap old hardware for new, so the capital tied up in each site stays exposed for years.
Cole Crawford, co-founder and chairman of compute market and index provider NativX, put the industry’s off-balance-sheet debt at just under $5 trillion and said “many more trillions of dollars” would be deployed over the next four years. But he warned that the scale of the underlying market did not guarantee that futures would attract enough trading to become liquid.
Carmen Li, chief executive officer of Silicon Data and Compute Exchange, two affiliated companies that offer a marketplace for trading compute and a set of price benchmarks, said the scale and pace of AI infrastructure investment had created a need for hedging mechanisms.
James Quinn, managing director at Galaxy, moderated the panel. He cited a Goldman Sachs estimate that $1 trillion will be spent on AI infrastructure this year.
Opaque prices
Nelms said prices still vary widely because compute is “such an opaque asset class today.” He expects the spread of data points to narrow once a futures market is established.
Even the market’s view of how compute prices will change over time is disputed.
Bahou said operators discount long-term reservations to win commitments from buyers who can plan only one or two years ahead. Because a shortage means there is in effect no spot market, capacity available immediately commands a large premium.
The result, he said, is a curve in backwardation, where near-term compute costs more than capacity booked further ahead. Over the medium term, however, the curve turns upwards as the premium for immediate access fades and expectations of higher prices take over.
Li said that until futures trade, the market has only a curve implied from reservation prices. “There’s no forward curve,” she said, adding that the implied curve is currently in contango, meaning later-dated prices are higher, for certain chips, whereas last year it sloped downwards across the board.
Nelms said ORNN’s data on long-term rental commitments cut against Li’s contango point. He said the price per GPU hour falls as the term lengthens and rises with the size of the cluster, and that ORNN intends to publish more of that data.
Crawford argued that GPUs are now relatively easy to get and that “time to electron”, or access to the power and infrastructure needed to run them, is what is scarce.
“You have a five-year forward curve on a depreciating asset in the GPU, and you have a 30-year underlying on a facility that is financed with very different economics and different returns,” he said.
What the contract should price
At the heart of the disagreement is a fundamental question: should a compute futures contract track the cost of particular GPUs, or the computing output they ultimately produce?
Quinn said futures would be cash settled, making the choice of underlying benchmark particularly important.
Crawford said GPU hours should be viewed as an input rather than an output and argued that chip-specific benchmarks would spread liquidity across hundreds of hardware variants. NativX takes a different approach. Its index is based on computing output rather than a particular GPU, using a normalised unit called “coil”, equal to 20 kilowatt hours of delivered capacity, which Crawford compared to the standard 42-gallon barrel used in oil markets.
When Crawford asked how a contract on one chip could cover exposure to others, Li replied that basis risk, where the price of a hedge does not move exactly in line with the exposure it is meant to protect, exists in every commodity market.
She said indices should be highly correlated, with basis relationships that are well understood, and that those correlations would emerge once futures trade. “Having some tool is better than having no tool,” she said.
Nelms defended chip-specific indices on behalf of financiers. Nelms defended chip-specific indices, arguing that financiers have exposure to specific hardware.
“There is no need to have a blended compute index that blends all Nvidia generations with all AMD generations,” he said. “At the end of the day you have very specific exposure.”
Bahou noted that crude oil has about a thousand published indices, and said compute is likewise “a great many things”. Compute Desk measures bulk rates rather than on-demand rates because bulk deals are what lenders, neoclouds and AI companies are exposed to, he said.
The providers also differ over how to calculate their benchmarks. Li said Silicon Data uses both completed transactions and prices visible in the market, while Nelms said ORNN puts greater weight on actual transactions because advertised prices do not show how much capacity is available or whether deals are actually being done.
Crawford said the benchmark has to outlive chip generations: “You have to standardise the hedge and not the hardware.”
Who will trade it
Crawford warned that a large potential market does not guarantee liquidity. “Numbers could be big, but that doesn’t automatically mean that it is going to have a deep futures market,” he said.
Bahou expects market makers, and perhaps ETF providers, to supply liquidity when contracts launch, but predicted a quiet spell before trading picks up because many of the natural buyers and sellers of compute have little experience of futures markets or the requirement to post margin as prices move.
He told futures commission merchants in the audience: “For the first time there is going to be a very new population that you can sell to, which is these AI companies and inference clouds.”
Li agreed this was a large opportunity for brokers. But she said the financiers that hold the servers on their balance sheets already know futures markets well and would take part from the first day.
Nelms said the operators most exposed to this risk often have the least capital to put up for hedges, opening a role for FCMs. He added that compute buyers would need educating on the benefits of locking in costs years ahead.
“I think certainty is something that we are lacking in compute,” he said.
